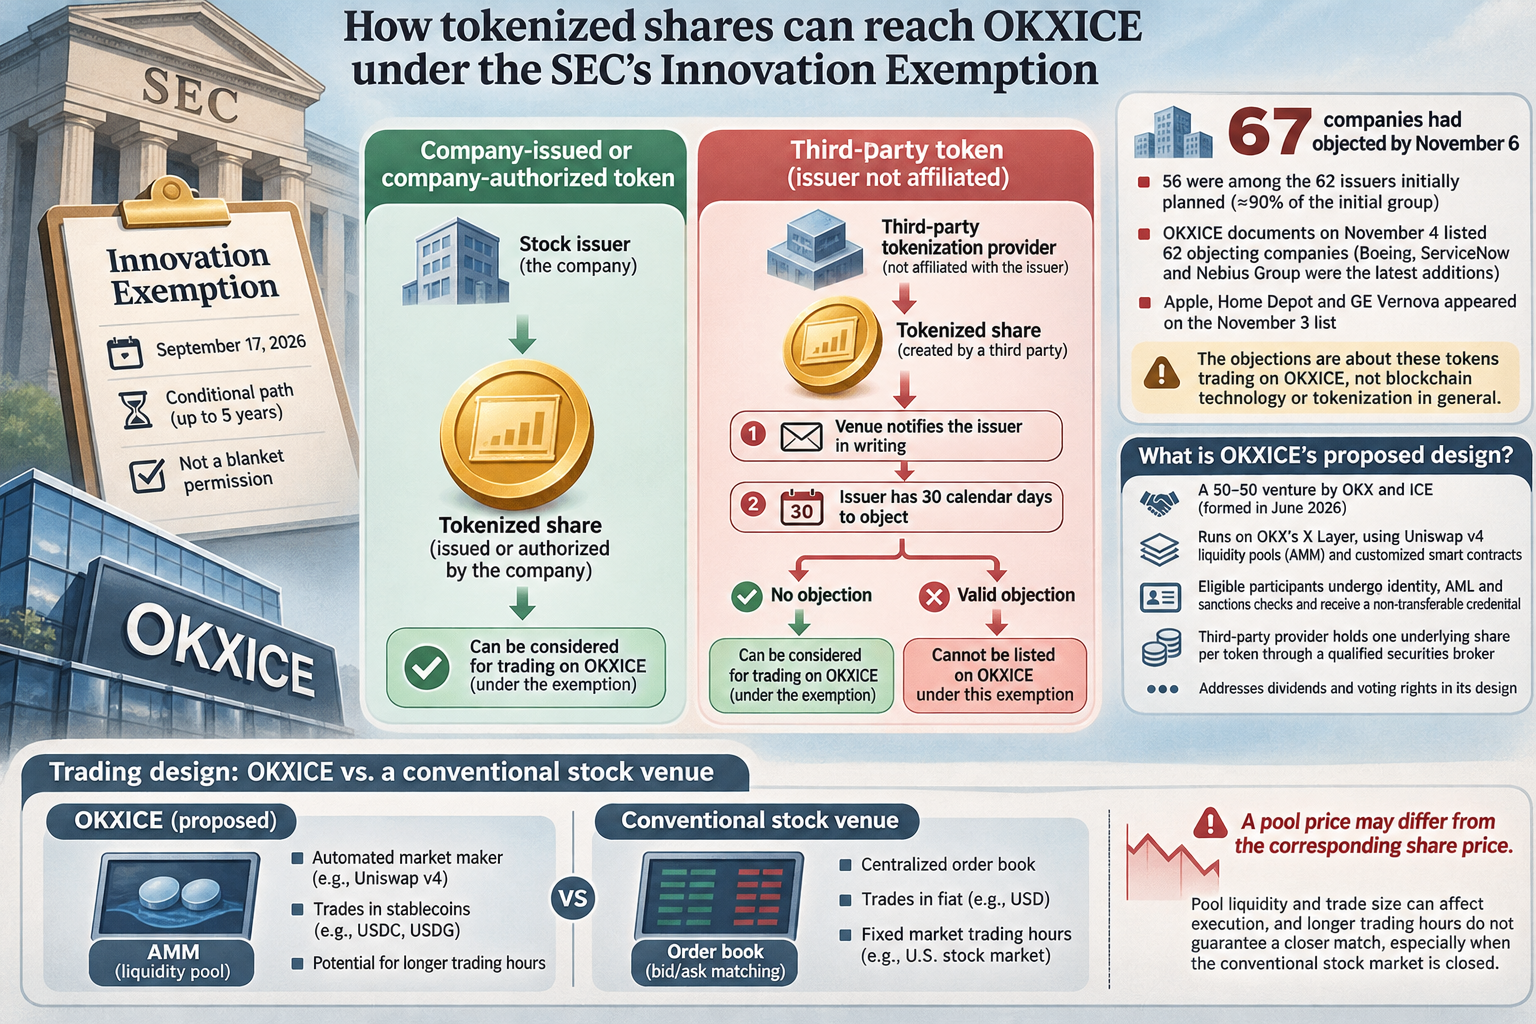
Originally reported November 7, 2026, at 20:30 (UTC+8). By November 6, 67 companies had objected to proposed trading of third-party tokenized versions of their shares on OKXICE, according to a CoinDesk count of the platform’s latest public notices cited in the original report. Fifty-six were among the 62 issuers initially planned for the platform—about 90% of that initial group. The objections concern these tokens trading on this venue, not blockchain technology or tokenization in general.
What does an issuer’s objection change?
The original report describes a September 17, 2026, US Securities and Exchange Commission “Innovation Exemption” that offers eligible tokenized-securities venues a conditional path lasting up to five years. It distinguishes tokens issued or authorized by the company behind the stock from tokens created by an unaffiliated third party. For the latter, the venue must notify the issuer in writing. If the issuer makes a valid objection within 30 calendar days of receiving notice, the token cannot be listed on that venue under this exemption. The arrangement is not blanket permission for stock tokenization.
The count was still changing when the article was published. OKXICE documents updated November 4 listed 62 objecting companies, with Boeing, ServiceNow and Nebius Group the latest additions; Apple, Home Depot and GE Vernova appeared on the November 3 list. The later count of 67 is the November 6 figure, not a separate measure of objections among the original 62 issuers.
How would OKXICE differ from a conventional stock venue?
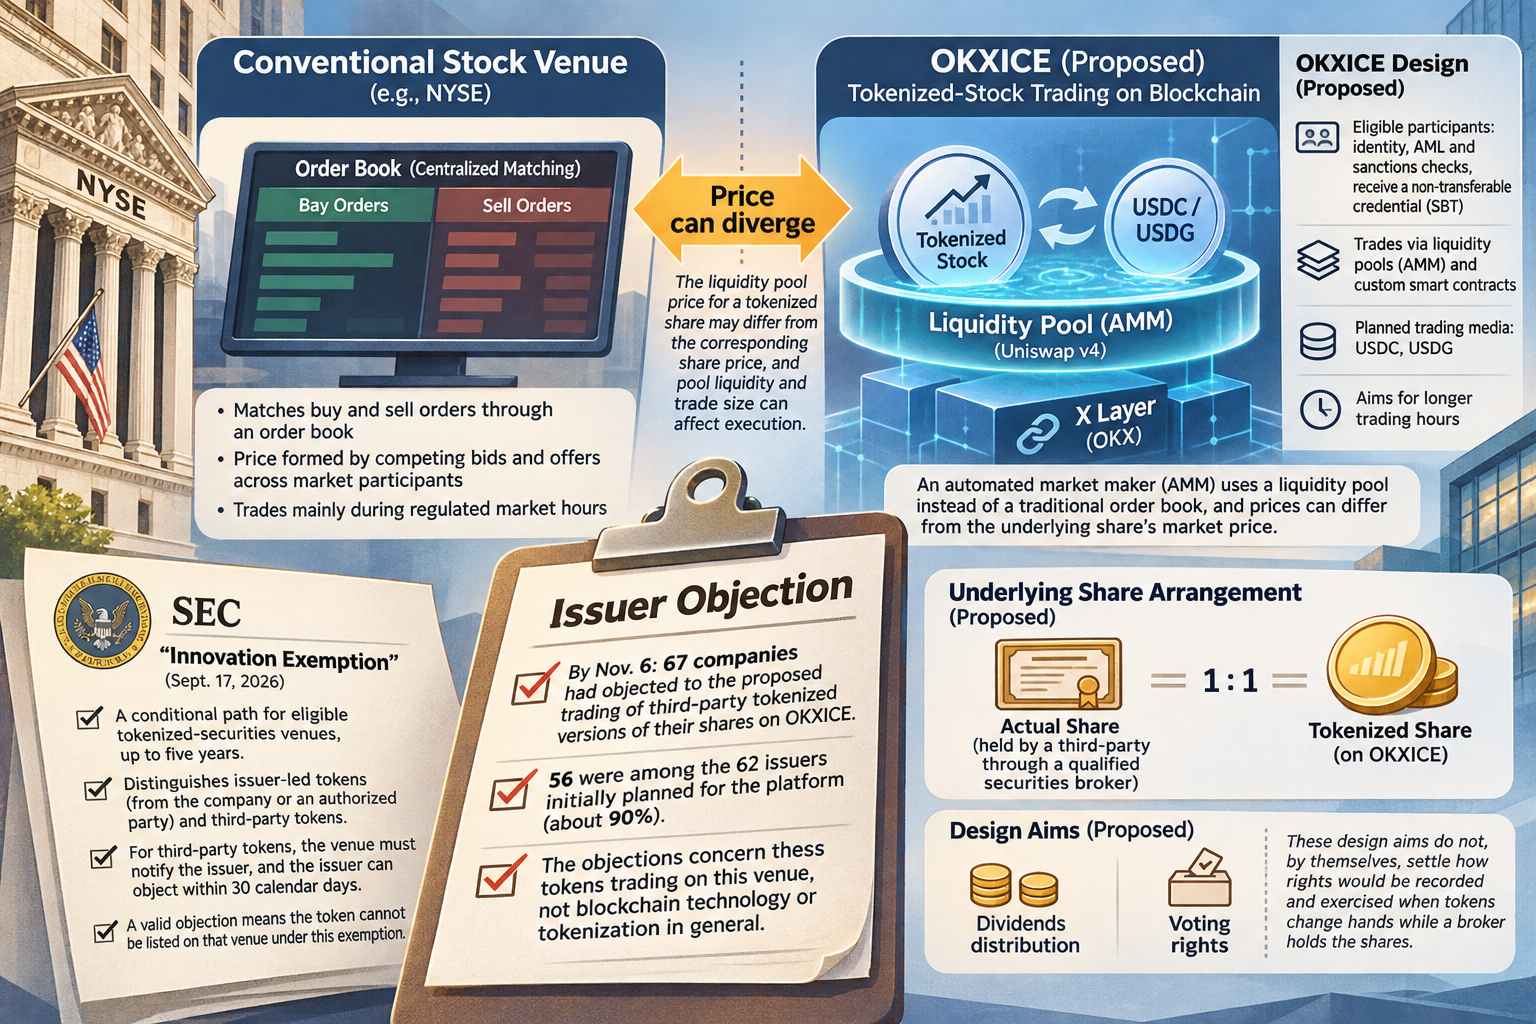
OKXICE is a 50–50 venture formed in June 2026 by crypto platform OKX and Intercontinental Exchange, the New York Stock Exchange’s parent company. Its proposed design would run on OKX’s X Layer and use Uniswap v4 liquidity pools and customized smart contracts rather than a conventional stock-market order book. Eligible participants would undergo identity, anti-money-laundering and sanctions checks and receive a non-transferable credential before trading or supplying liquidity. USDC and USDG are among the planned trading media.
Under the proposal, a third-party tokenization provider would hold one underlying share for each token through a qualified securities broker. Platform documents also address dividends and voting rights. Those design aims do not, by themselves, settle how rights would be recorded and exercised when tokens change hands while a broker holds the shares.
An automated market maker also changes the price-formation question. Pool liquidity and trade size can affect execution, and OKXICE’s own documents warn that a pool price may differ from the corresponding share price. Longer trading hours would not guarantee a closer match, particularly while the conventional stock market is closed.
The public documents do not give each company’s reason for objecting. An objection under this exemption should therefore not be read as a permanent rejection of tokenized shares or as support for any single explanation. It does show a practical distinction between making a share-backed token tradable and securing the issuer’s acceptance of that third-party trading arrangement.
Source: panewslab.com (originally published 2026-11-07 20:30 UTC+8)