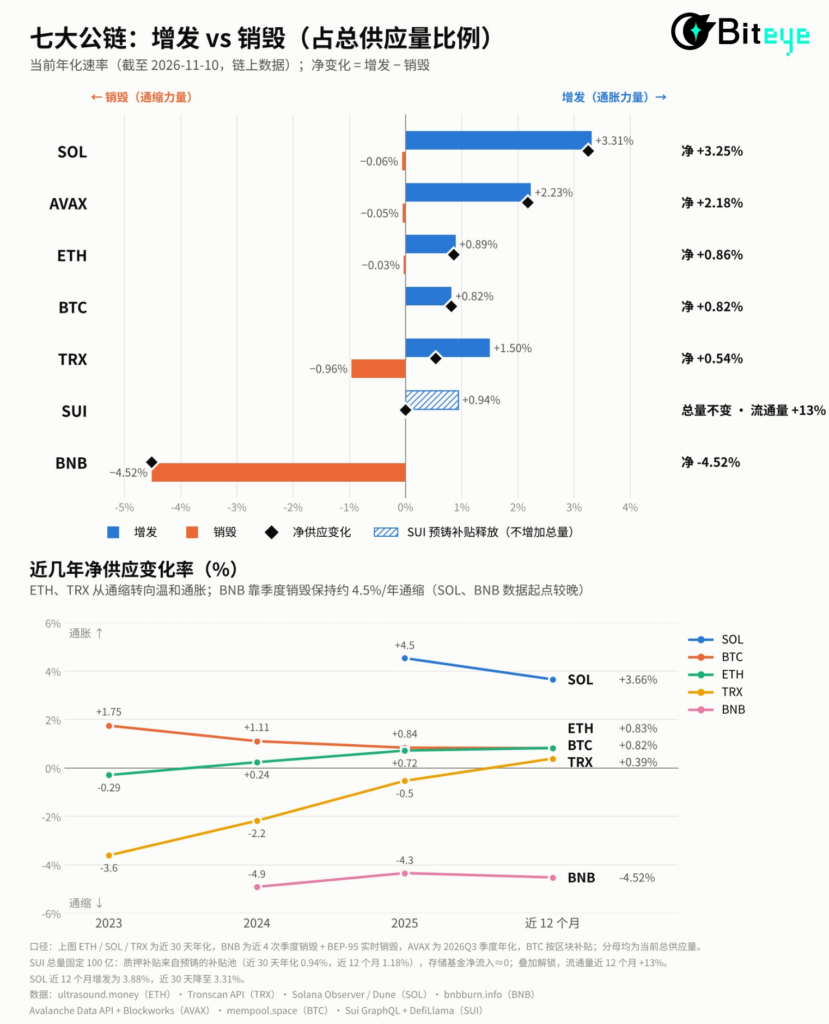
Historical comparison based on a Biteye article published November 11, 2026, at 11:03 (UTC+8). Figures and time references below reflect that report, not current supply data.
The comparison question: Does network activity reduce each token’s supply? The answer depends on what is issued, what is burned, and whether other mechanisms—such as unlocks—change circulating supply.
| Token | Supply mechanism described in the original report | What fees or activity change |
|---|---|---|
| BTC | Supply is capped at approximately 21 million, with block rewards halving roughly every four years. At a 3.125 BTC block reward and an average ten-minute block interval, the report estimated about 164,300 new BTC a year, or 0.82% annual supply inflation. | The report does not describe a fee-burn mechanism for BTC. |
| ETH | Validator issuance continues after the 2022 Merge. The report put cumulative supply growth since the Merge at about 1.37%. | EIP-1559 burns base fees. In the 30 days preceding the report, burns offset only about 3.2% of new issuance, amid wider L2 use and lower gas fees. |
| SOL | Solana’s stated inflation schedule began at 8% annually, declines by 15% each year, and has a long-term target of 1.5%. | Burns briefly exceeded 10,000 SOL a day during the 2024 meme-token boom and offset about 23% of issuance in January 2025. After SIMD-0096, validators receive all priority fees while 50% of base fees are burned; daily burns subsequently fell as low as roughly 700 SOL. |
| BNB | The report describes no continuing issuance. Quarterly Auto-Burn and BEP-95 fee burns reduce supply toward a target of 100 million BNB. It reports approximately 6.2 million BNB burned across the first four quarterly burns of 2026. | Auto-Burn depends on price and block production; BEP-95 burns part of network fees. |
| TRX | Block rewards issue TRX, while user-paid Energy and Bandwidth resource fees are burned. | Users can instead obtain resources through staking or rental. More USDT transfers therefore do not necessarily mean proportionally more TRX burned. |
| AVAX | Supply is capped at 720 million. Validator rewards issue AVAX, while fees on the primary network’s X-, C- and P-Chains are fully burned. | By early November 2026, the report counted roughly 474 million AVAX minted, including about 114 million in staking rewards, and about 5.18 million burned cumulatively. Burns had not offset issuance. |
| SUI | Total supply is fixed at 10 billion; unlocks, rather than unlimited issuance, are a key driver of circulating supply. | The Storage Fund locks part of storage fees and uses staking returns to compensate validators. Most fees can be recovered when data is deleted; the remainder stays in the fund rather than being permanently burned. |
These are different measures: an issuance rate is not a net supply-change rate, a cumulative burn is not an annual burn, and a token unlock is not new issuance. The figures above should not be read as a single-period ranking.
Why ETH’s burn is not a valuation floor
The report discusses a model Vitalik Buterin revisited in an X post on November 8: token valuation = annual value burned ÷ discount rate. At a hypothetical $1 billion burned each year and a 4% discount rate, the result is $25 billion. Buterin argued that fee burns are not a dependable valuation floor because substantial past fees came from speculative crypto activity that can contract. He supported retaining EIP-1559, but said even burns persistently below 10% of issuance would not justify deliberately raising fees at the expense of Ethereum’s decentralization and long-term development.
The source contrasts approximately 1.48 million ETH burned in 2022, valued at about $3.6 billion, with roughly 19,200 ETH, valued at about $43 million, burned in 2026 through November 8. Its illustrative annualization of the latter to about $50 million yields $1.25 billion at the same 4% rate—more than 200 times below the approximately $270 billion ETH market capitalization it cited for that period. This is a demonstration of the model’s limits, not an estimate of ETH’s current value.
Buterin instead emphasized decentralization, censorship resistance, open source, privacy and security as potential sources of Ethereum’s long-term value, particularly as AI develops. The report also raises a counterquestion: ETH’s roles as collateral, a medium of exchange and a native asset for financial infrastructure may create demand, but its supply has no fixed cap and its issuance rules can change through protocol upgrades. Neither fee burns nor a possible monetary premium supplies a uniform valuation rule across these networks.
Source: panewslab.com (originally published 2026-11-11 11:03 UTC+8)